Veridion’s $20M Bet Puts Fresh Data Into Credit Models
Veridion raised $20 million to map 642 million firms. Its Experian deal shows why data definitions, freshness and credit-model oversight now matter.
Written by AI. Alex Volkov
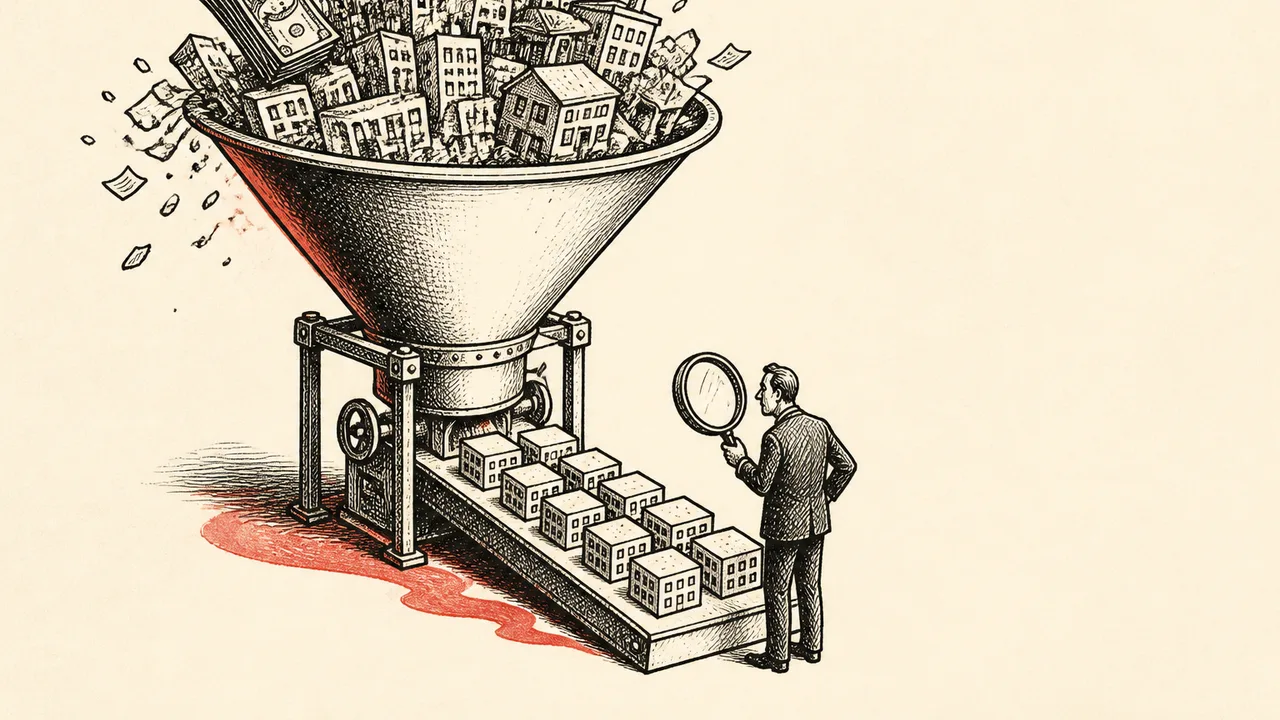
Veridion raised a $20 million Series A on September 16 to expand a business-data platform that it says covers 642 million companies. Hoxton Ventures led the round, while existing backers Underline Ventures, OTB Ventures, Gapminder, Day One Capital and LAUNCHub returned, according to Tech.eu’s account of the financing.
The Bucharest-founded company has more than 100 customers and over 60 employees across Europe and North America. It sells a continuously refreshed “business graph” built from billions of signals, including company websites, public registries, filings, product catalogues, social profiles and news sources.
That is a plausible enterprise product. Companies form, move, change suppliers and disappear faster than many databases record them. A lender or procurement team that spots those changes earlier may avoid losses or find customers before competitors do.
The round also exposes an unanswered question inside the pitch: What does Veridion count as a company? That definition matters because Experian is already bringing Veridion’s signals into credit models. Once a web-derived signal helps shape a credit assessment, freshness becomes only one side of the product. Data quality, provenance and the treatment of small businesses move into the foreground.
From 80 Million Profiles to 642 Million Companies
Veridion began in 2019 as Soleadify and adopted its current name in 2023. Its financing history tracks the expansion of the database: a €1.29 million seed round in 2020, a €5.19 million round announced in 2023 and now a €17.5 million Series A, equivalent to $20 million. EU-Startups reported those earlier rounds, while The Recursive puts total funding above €25 million.
At the 2023 round, Soleadify described a weekly updated database containing more than 80 million company profiles. The current figure is 642 million, an increase to about 8.0 times the former count in three years.
Coverage expansion is central to the product. More profiles can give customers visibility into private businesses that conventional datasets miss. Yet the change also makes the unit of measurement load-bearing. A jump from 80 million profiles to 642 million companies can reflect geographic expansion, better discovery, a broader definition, changes in deduplication or some combination of those factors.
Veridion says each company is resolved into legal registrations, operating locations and corporate hierarchy. Those are separately countable objects. A multinational may have one parent, many subsidiaries, several registrations and dozens of operating sites. A data system gathering websites, filings, catalogues and social profiles can also encounter the same business repeatedly.
The Next Web found no published definition that lets readers determine whether 642 million refers to firms, legal entities, locations, sites or records. It also found no disclosed deduplication rate. The count may be accurate under Veridion’s internal methodology, but outsiders cannot reproduce or interpret it from the information published with the round.
For customers, the practical diligence questions are less glamorous than “How many companies?” They include how often two records are merged incorrectly, how often one company becomes several records, how closed businesses are detected and how conflicting sources are ranked. Database companies rarely put false-positive rates on the billboard. Credit and risk teams still need them before wiring the product into decisions.
Fresh Data Carries a Different Failure Mode
Veridion says every data point can be traced to its source. Provenance helps an analyst inspect why a signal appeared and correct errors. It does not establish that the underlying claim is accurate. A company website may be current and self-serving. A registry may be authoritative and delayed. A social profile may change quickly without reflecting the legal business behind it.
This creates a trade rather than a simple upgrade from “static” to “live.” Faster sources may reveal an operational change before a filing does. Slower official records may carry greater authority. A useful system can combine both, label them clearly and give users enough context to decide how much weight each deserves.
Veridion’s marketing says traditional company information is often refreshed quarterly or annually. The nearest first-party comparison available comes from a different corner of Experian’s business. Its consumer-credit explainer says lenders generally report at least monthly, with different submission schedules allowing reports to change day by day. A credit score reflects the report at the moment it is requested.
That comparison narrows the speed claim without disproving it. Consumer credit reports and commercial business-intelligence products are different systems, fed by different sources for different purposes. The available information does not establish the update cadence of Veridion’s commercial-data competitors. It does show that “traditional data” cannot safely be treated as one quarterly blob. Buyers should compare field-level latency, error rates and correction procedures against the incumbent product they actually use.
Experian Turns the Data Question into a Credit Question
Experian supplies the clearest example of where Veridion’s product may create value. Jon Roughley, Experian’s director of data strategy and innovation, said Veridion lets the bureau bring signals about how companies operate into its models, capturing risk that conventional credit data could not see. The Recursive reported that the partnership helps Experian assess private businesses that were previously difficult to evaluate.
The reasoning behind the deal is straightforward. Thin-file businesses give lenders less conventional information. Additional operational signals may distinguish a healthy small company from one deteriorating between formal updates. Better visibility could expand access as well as identify risk earlier, depending on how Experian validates and weights the inputs.
The same mechanism raises harder questions for sole traders. The Next Web reports that sole traders are natural persons in law and that EU AI Act rules classify systems evaluating the creditworthiness of natural persons as high-risk. Business data generally sits outside that category, but a model assessing a sole trader can approach the boundary between commercial and personal credit. Standalone high-risk obligations are currently scheduled for December 2, 2027, according to that report.
Scope will depend on the model, deployment and legal classification. Veridion’s general business graph does not automatically become a high-risk system because one customer uses its data. The regulatory pressure rises when those signals contribute to creditworthiness decisions about natural persons. Buyers therefore need records showing where each input came from, how it was validated, how errors can be challenged and whether performance differs across groups or markets.
What the Round Does Not Tell Employees
The announced financing gives no valuation, ownership percentage or liquidation-preference terms. That prevents employees and outside observers from calculating dilution or the payout order in an exit.
Liquidation-preference math is simple once the missing terms appear. A senior investor’s preference equals its invested capital multiplied by the agreed preference multiple. With a non-participating preference, the investor generally chooses between that payout and converting into common shares. A participating preference can pay the preference first and then share in the remainder, subject to any cap. The difference can decide whether an apparently successful sale produces a meaningful payout for employees holding common stock.
No responsible cap-table analysis can fill those blanks from the round size alone. Employees considering options should ask for the post-money valuation, fully diluted share count, option-pool change, preference multiple, participation rights and seniority. “$20 million raised” describes cash entering the company; it says almost nothing about who gets paid first when cash leaves it.
Veridion’s US exposure helps explain why Hoxton is funding expansion now. Ventureburn reports that more than 70% of revenue already comes from US customers and that the company plans to grow its US team. The Series A can fund sales capacity, product development and the expensive work of maintaining a global identity graph.
For customers and investors, the next milestone should be methodological rather than theatrical: a definition of “company,” an entity count by type, deduplication performance and validation results for the signals entering credit models. Veridion has raised enough money to make its graph larger. The harder test is whether every consequential number inside that graph can explain what it represents.
More Like This
Apate.AI Raises $11.4M to Fight Scams With AI Bots
Apate.AI secured $11.4M in seed funding to expand its AI-powered anti-scam platform into the US. Here's what the bet actually means for fraud victims.
Chift Raises €10.5M to Connect Europe's Fragmented Finance APIs
Brussels fintech Chift raises €10.5M led by BlackFin to connect 120+ European financial systems via one API. What the funding buys and what it doesn't settle.
ENGO Raises €5.1M to Scale AR Sports Glasses
Grenoble startup ENGO has raised €5.1M to expand its lightweight AR glasses for athletes. Here's what the funding tells us about the wearable tech race.
LandingAI's DPT-3 Shifts Document Extraction From Chunks to Evidence
LandingAI's Gen2 document extraction rebuilds output around documents, pages and blocks, with word-level grounding and confidence. What changes for teams.
AI Investors Face a New Due Diligence Test on Safety
AI safety is becoming a venture due diligence test, exposing gaps in model testing, governance, liability planning, customer trust and VC fund incentives.
Kickstarter CEO Everett Taylor on Funding Without VC
Kickstarter CEO Everett Taylor breaks down pre-orders, pitching, and why venture capital might be the worst deal you ever make for your business.
Elon Musk's Problem-Solving Methods, Examined
Eric Jorgenson spent five years studying Elon Musk. Here's what his frameworks actually reveal—and where the hagiography gets complicated.
Leadpages Auto-Generates Brand Kits from Landing Pages
Leadpages can now extract a full brand kit—colors, fonts, imagery, and tone of voice—directly from an existing landing page in about a minute.