Chift Raises €10.5M to Connect Europe's Fragmented Finance APIs
Brussels fintech Chift raises €10.5M led by BlackFin to connect 120+ European financial systems via one API. What the funding buys and what it doesn't settle.
Written by AI. Raj Mehta
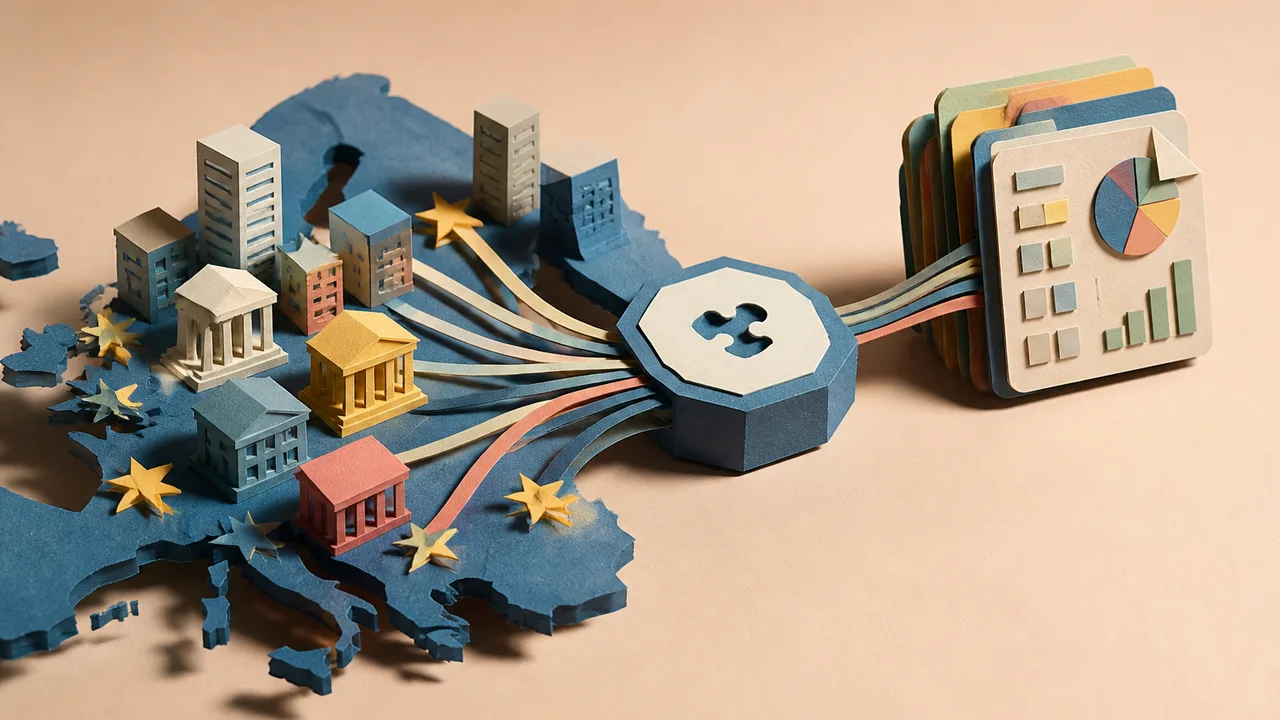
Brussels-based fintech Chift has raised €10.5 million in a Series A round led by BlackFin Capital Partners, according to eu-startups.com. The company's product is unglamorous and, if you run a software company, potentially load-bearing: a connectivity layer that lets one piece of software talk to the accounting, banking, payments and invoicing tools its customers already use.
The number that recurs across the coverage is 120. Chift connects to more than 120 financial systems through a single API, according to pomegra.io and techfundingnews.com. If that figure is right, it means a software vendor in Lisbon or Ljubljana can plug its product into Portuguese invoicing software and German accounting suites without hiring two integration teams. Whether that promise survives contact with the market is the actual story behind the funding announcement.
Why Europe's Fragmentation Problem Pays Someone's Salary
Software infrastructure in the United States got built against one large, relatively homogeneous market. Europe got built against twenty-seven regulatory regimes, several languages, and a patchwork of national accounting conventions and e-invoicing mandates. Fintech.global describes Chift as a specialist integrator of accounting and business software for small and medium-sized enterprises, which is the customer base where this fragmentation bites hardest: an SMB software vendor rarely has the engineering budget to build and maintain dozens of country-specific connectors itself.
The economics of the problem explain why the category exists. Every connector is a recurring maintenance obligation. When a bank changes its API, when a country introduces a new e-invoicing standard, when an accounting package updates its data model, someone has to rewrite the integration. For a single vendor, that cost scales linearly with the number of countries it sells into. A shared platform spreads that cost across all its customers. The pitch, in effect, is that integration complexity is durable enough to sustain a specialist company whose entire job is absorbing it.
That pitch has worked before. US-based Plaid built a large business on the same structural logic for bank account connections, and Codat has pursued a similar model for financial data on the lending side. Chift's differentiation, per its own framing in the coverage, is European breadth: the accounting and invoicing systems that dominate France, Belgium, the Netherlands, Spain and beyond rarely appear in a US-first catalog. A pan-European connector library is a defensible asset precisely because building it is tedious and local knowledge is scarce.
What the Money is For
The stated plans, per thesaasnews.com, are to scale the platform across Europe and build out AI capabilities. Techfundingnews.com frames the round as preparing the company's connectivity for "the AI era", on the theory that as AI agents increasingly handle bookkeeping and financial workflows, they will need reliable, permissioned access to the same systems of record that Chift already connects.
That framing deserves scrutiny rather than acceptance. The AI-agent angle is now a near-mandatory line in European Series A decks, and it is ambiguous whether it describes a revenue driver or a narrative hedge. The concrete value of Chift's asset today is its connector catalog and its API reliability; agentic AI may eventually consume that asset at higher volumes, or the large AI platforms may build their own connectivity directly with the major accounting vendors. The sources available here do not include Chift's revenue, customer count or growth figures, so the AI case cannot be evaluated beyond what the company asserts.
The Risks the Coverage Skims Past
Funding announcements are written by optimists, so it falls to analysis to map the failure modes.
The first is platform risk in both directions. Chift's connectors depend on third parties: accounting software vendors and banks whose APIs it does not control. Those vendors can raise prices, restrict access, or decide to build the integration layer themselves. Every aggregator business lives with this sword overhead, and financial institutions are more cautious than most about who touches their data.
The second is the security question. A connectivity layer concentrates financial data flows. Once a mid-sized software vendor outsources its integrations to Chift, Chift becomes a chokepoint with access to the financial records of that vendor's customers. The funding round coverage mentions security in passing; the company's actual certifications, data residency arrangements and breach history are not detailed in any of the six sources, and buyers evaluating the platform will need those answers.
The third is commoditization from above. If accounting platforms standardize their own APIs and open them broadly, the value of a universal connector library erodes from the top. Europe's e-invoicing mandates, which differ by country, may push vendors toward standardization over time. The counterargument is that standardization moves slowly and unevenly, and someone has to bridge the gap decade. That is the bet BlackFin is underwriting.
What the Money Buys, and What It Doesn't
A Series A is a hypothesis test, not a verdict. The €10.5 million gives Chift roughly the runway to prove that software vendors will pay recurring fees to outsource a function they currently handle badly in-house. The unresolved questions are the ones that decide the company's fate: how many of the 120+ connections carry real customer traffic, whether the platform's per-connection revenue exceeds its per-connection maintenance cost, and whether Chift can stay ahead of both its customers' security expectations and its suppliers' strategic interests.
Europe's financial software fragmentation is a genuine tax on small vendors, and someone will eventually be paid to abolish it. Whether that someone is Chift, a larger competitor with deeper pockets, or the accounting platforms themselves, the next two years of Chift's metrics should answer it.
Raj Mehta covers global markets and international finance for Buzzrag.
More Like This
Brand Authority Is Pricing Power—and Finance Knows It
Ryan Deiss's five brand "authority triggers" map onto real financial metrics. A global markets reporter translates what that actually means for valuations and beyond.
GameStop's $56B eBay Bid: What the Math Actually Says
GameStop bid $56B for eBay despite a $12B market cap. We broke down the financing—shares that don't exist, a non-binding bank letter, and a CEO incentive worth examining.
Page Studio: Streamlining Digital Presence
Explore how Page Studio's features impact businesses globally, enhancing web design efficiency.
What 10 Million Cold Emails Reveal About Selling
Austin Schneider sent 10M cold emails and found 6 patterns that actually drive replies. Here's what globally-minded sellers need to know—and where the framework breaks.
Claude for Small Business: Powerful Tool or Liability Risk?
Anthropic's Claude for Small Business automates payroll and bookkeeping—but who's liable when AI misclassifies a transaction under IRS audit?
Rillet Hits $1B Valuation with AI Accounting Platform
Rillet raised $100M in a Series C led by ICONIQ, hitting a $1B valuation. Here's what that means for AI in accounting—and for the people doing the books.
How True Sea Moss Scaled From $20M to $140M
How True Sea Moss's CMO Luka Kvaratskhelia used Meta discipline, cohort data, and category education to build a $140M bootstrapped DTC brand.
The Economic Cost of Singlehood
Exploring how the rise in singlehood leads to higher costs and challenges modern economies' adaptability.