Aging Populations Force Hard Choices for Public Budgets
Moody's sees Western populations shrinking from 2029. Aging may strain pensions and health care, leaving governments to decide which households pay more, and when.
Written by AI. Jonathan Park
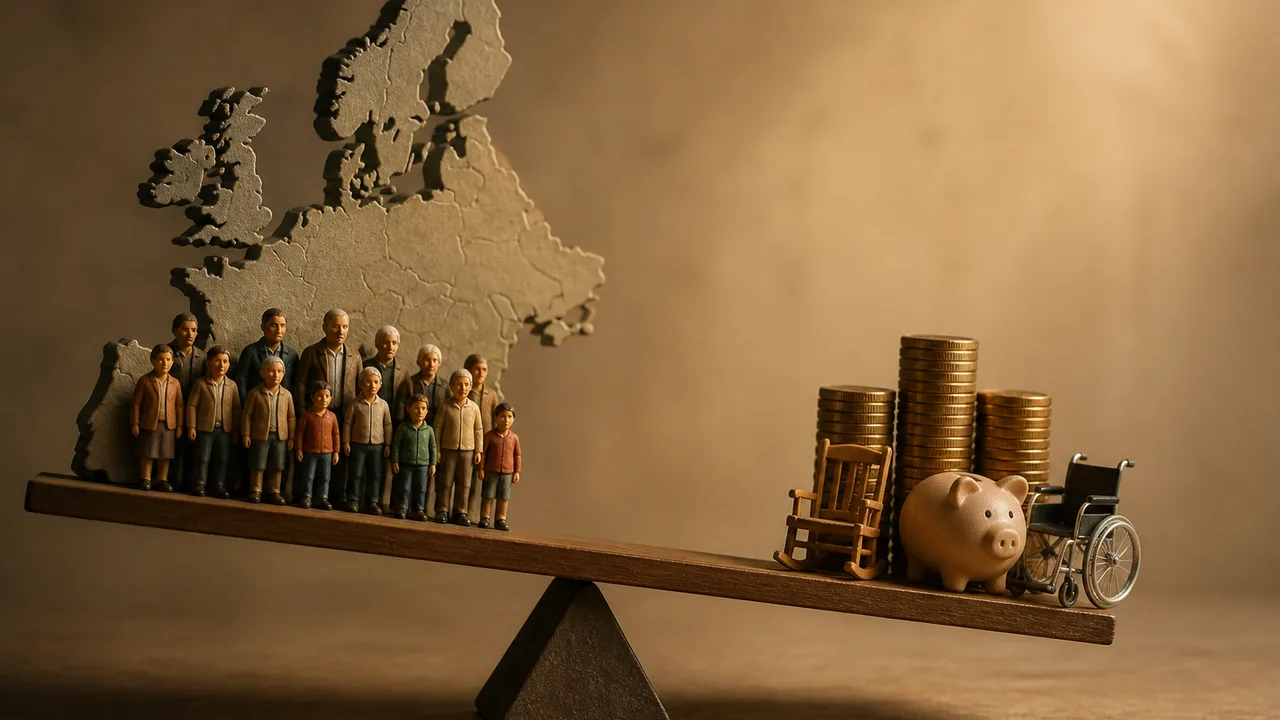
The European Union’s population could peak as soon as 2029, and Moody’s warns that aging Western populations will strain public finances well before they start to shrink, CNBC reported. For a worker looking at a payslip, 2029 may sound distant. For a government promising pensions and health care decades from now, it is close enough to demand an answer: who will pay if the number of workers grows more slowly than the number of older residents?
The squeeze develops gradually. People living longer can draw retirement benefits and use health services for more years. Low birth rates can leave fewer people entering the workforce behind them. If the working-age population contracts, governments may have less growth in income-tax and payroll-tax receipts just as age-related spending rises. The precise effect depends on employment, wages, tax rules and the design of each country’s benefits. A population forecast identifies the pressure; elected officials decide where it lands.
That last step deserves more scrutiny than a date on a demographic chart. Governments can ask workers to contribute more, retirees to accept smaller benefits, people to work longer, or future taxpayers to service more debt. They can also try to expand employment and productivity. Each option reaches a different household, and the people with the least flexibility may face the highest cost.
The Worker-to-Retiree Ratio Has Limits
Public pension systems often rely, at least in part, on taxes collected from people working now to pay benefits to people who have already retired. Health-care spending can add pressure because an older population generally needs more care.
Still, a head count cannot tell a finance minister how much revenue will arrive. A working-age resident who cannot find a job contributes differently from one earning a high wage. Higher pay can increase tax receipts even if the number of workers falls. Pensioners may also pay taxes, including taxes on purchases or income, depending on the country. Treating everyone over a retirement threshold as a pure budget cost obscures those differences.
The spending side varies too. A country with generous public pensions has made a different promise from one that expects households to fund more of their own retirement. A government that provides broad public health coverage carries costs that another may leave with insurers, employers or patients. Shifting an expense off a government balance sheet does not necessarily make it cheaper for the person receiving the bill.
That is why a useful budget debate should show more than the projected number of older residents. It should show the expected workforce, wages, tax receipts, pension commitments and health spending over the same years. Then it should show what happens if employment or productivity grows more slowly than assumed. Otherwise, a forecast can turn into a convenient explanation for a policy choice that officials have yet to defend.
Five Ways to Send the Bill
Raising taxes or pension contributions protects promised benefits, but it reduces what workers take home. The design determines who feels it most. A higher payroll contribution comes directly out of a payslip or adds to an employer’s labor costs. A broader tax increase may spread the burden across more sources of income or spending. Either way, officials should name the households expected to pay, rather than announcing that “revenue” must rise.
Reducing benefits can contain public spending while transferring risk to retirees. A person with savings may absorb a smaller pension. Someone relying on that payment for rent, groceries and utilities has fewer ways to adjust. Timing is part of the decision: cutting benefits for people already retired gives them little opportunity to save more, while changing rules for younger workers gives them time but can still upend plans built around earlier promises.
Raising the retirement age changes both sides of the ledger. People who work longer may pay taxes for longer and claim pensions later. Yet consider a proposal to move eligibility from 65 to 67. A desk worker with the option to stay employed might gain two more years of wages. A warehouse worker whose health prevents two more years on the job could spend that period drawing down savings, relying on family or seeking another form of support. The same rule can postpone one person’s retirement and remove another person’s income.
Borrowing gives governments time to phase in changes and can spare current households an abrupt tax rise or benefit cut. It also creates interest costs and leaves future budgets with less room to maneuver. Whether that trade is prudent depends on borrowing costs, economic growth and what the money buys. Borrowing to help people work longer and more productively presents a different prospect from borrowing indefinitely to cover a gap that keeps widening.
Immigration can add workers and taxpayers, while policies that help more residents enter or remain in paid work can widen the contribution base. Neither works by decree. New arrivals need housing, services and access to jobs; parents need workable care arrangements; older workers need employers willing to hire them. Those costs and obstacles belong in the fiscal calculation alongside the hoped-for tax receipts.
Longer Lives Change the Question
Europe’s aging population already poses policy challenges, but the economic outcome is not fixed by the age chart. Economist Andrew J. Scott argues that aging populations need not produce weaker economies. That is a useful challenge to any forecast treated as destiny: a society can change how it works, saves and supports people through longer lives.
It also puts demands on that optimistic case. If governments expect people to remain employed later in life, they need to examine whether suitable jobs exist and who can perform them. If they expect higher productivity to sustain tax receipts, they need to show how that growth reaches wages and public revenue. An economy can produce more per worker while leaving a government’s pension commitments difficult to finance under its existing tax rules.
Nor will every country face the same timetable or have the same choices. Differences in birth rates, employment, immigration, pension design and health coverage change the size and shape of the problem. The EU’s projected 2029 peak is a broad forecast, not a date when every treasury receives an identical invoice. Its practical value is to force governments to publish the assumptions behind their promises while there is still time to change course gradually.
The fairest test of any proposed fix is concrete: whose monthly income changes, when does it change, and what can that person do about it? A minister can call a later retirement age sustainability; the warehouse worker facing two years without a pension will experience it as a lost payment. A minister can call a contribution increase shared responsibility; the worker watching a smaller payslip will know the amount. Demography creates the pressure. Policy determines whose household absorbs it.
More Like This
High Mortgage Rates Stall Housing Market Recovery
Three in five homes listed since January remain unsold as mortgage rates above 6% freeze out buyers. Here's what the data reveals about who pays the price.
USMCA Won't Be Renewed: What Annual Reviews Mean
The Trump administration has blocked USMCA's 16-year renewal, opting for annual reviews. Here's what that means for trade, business, and North America.
Bill Ackman's Art of Finding Invisible Money
Explore Bill Ackman's strategy of finding hidden value in companies, beyond standard metrics.
September Jobs Slowed as Stocks Bet on a Fed Pause
September's weak hiring lifted hopes of a Fed pause and stocks rose. The same figures point to a tougher job search, while inflation keeps the rate outlook open.
Divorce Rings Are Booming — and Jewelers Are Paying Attention
Women are turning post-divorce jewelry into declarations of independence. What's driving the divorce ring trend—and who's really selling it?
The Hidden Economic Cost of Performing Masculinity
Jordan Ritter Conn's book "American Men" maps masculinity's psychological toll—but the financial machinery behind male insecurity deserves equal scrutiny.