Youth Sports Facilities: When Ambition Becomes an Asset Class
Investors call youth sports facilities recession-proof. The economics of real estate, utilization, and pay-to-play tell a more complicated story for families.
Written by AI. Alex Volkov
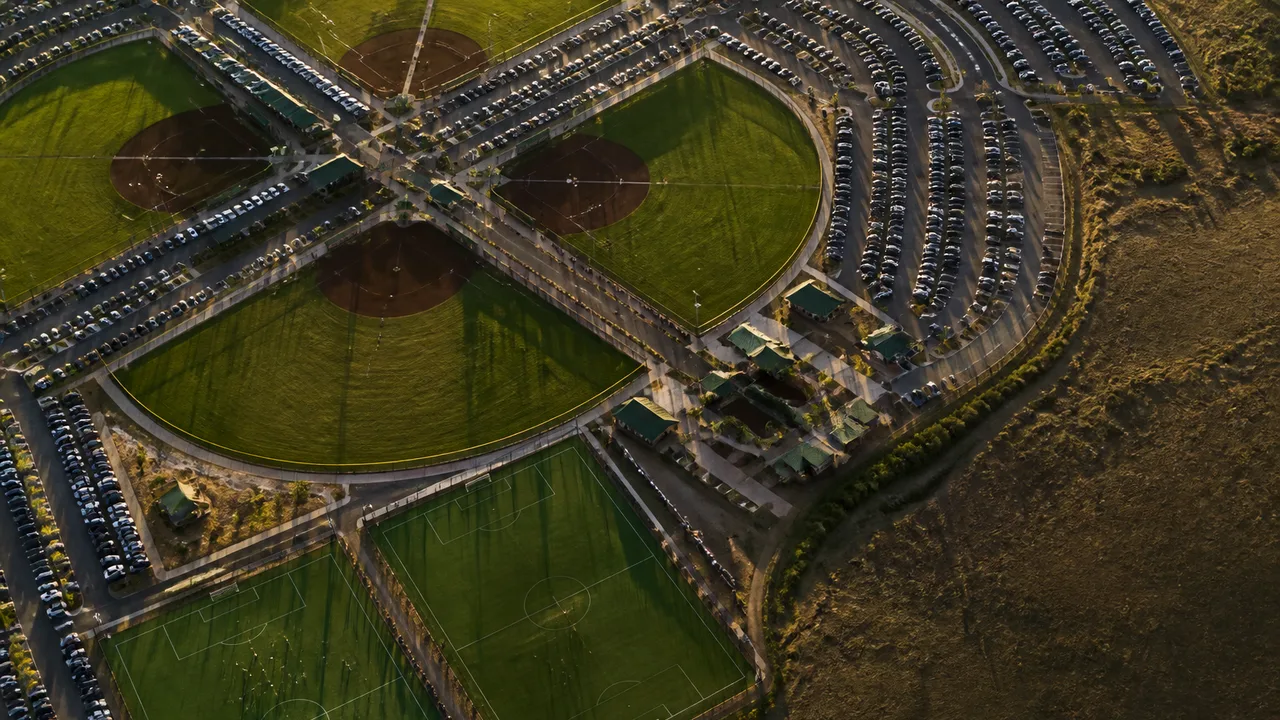
One facility owner told Morning Brew that youth sports is "recession-proof," and that single phrase is doing a lot of load-bearing work across the sector right now. Investors and operators are pouring money into increasingly elaborate training complexes, betting that parents will keep paying for tournaments, coaching, and the remote possibility of a collegiate scholarship or professional career before they cut almost any other line in the household budget.
The pitch is coherent. The bet deserves scrutiny. This piece maps both: the bull case the operators are selling, the cost structure they carry, and the families who fund the whole thing.
The Bull Case, Stated Fairly
Start with what the operators get right. Youth sports participation is close to non-discretionary for many households in a way that restaurant meals and vacations are not. A family that commits to a travel soccer calendar in August has already paid deposits, bought cleats, and arranged carpools; by February, most of that spend is sunk. Aspiration also has a defensive quality. Parents rationalize it as investment in a scholarship, in college admissions, or simply in a kid's mental health during a screen-saturated childhood. Spending framed as investment behaves differently in a downturn than spending framed as luxury.
The facility model also has a genuine structural advantage over, say, a boutique fitness studio: demand comes from multiple sports with offsetting seasons. A well-run dome can host soccer in winter, lacrosse in spring, and football camps in summer. Utilization, not amenities, drives the margin. Morning Brew's reporting captures the sector's core logic: elaborate facilities are the visible layer on a business that lives or dies on whether the building stays busy across age groups and sports.
What 'Recession-Proof' Leaves Out
Now the balance sheet. A facility is real estate, and real estate is leveraged, fixed-cost, and local. Rent or debt service gets paid whether or not a single travel team books January weekends. Staffing costs persist. Indoor facilities in northern states face brutal seasonal concentration: revenue clusters in winter, while summer competes with outdoors and costs run all year.
Then there's the household budget itself. The claim that parents cut elsewhere first is empirically testable, and history offers a mixed verdict. In the 2008-2010 downturn, youth sports participation held up better than most discretionary categories, but travel-team enrollment in some regions thinned, and programs in less affluent areas absorbed disproportionate cuts. Resilience is uneven; the family pulling a kid from a $4,000-per-year club team does not make the local news.
The Utilization Math
If you want to evaluate any of these facilities as a business, ignore the turf quality and ask three questions. First, what percentage of available hours are actually booked? A facility running at 40% utilization with a mortgage is a slow-motion writeoff; one at 80% with tiered pricing (peak hours for teams, off-peak for individual training and birthday parties) can carry real margin. Second, how many revenue streams stack in the same square footage? Rentals, academies, tournaments (which also fill hotels and restaurants, earning the operator political goodwill), camps, and retail all improve the math. Third, who is the anchor tenant? A facility with a committed club operating inside it has guaranteed baseline revenue; a standalone building is a bet on cold bookings.
Morning Brew notes the winners may be owners who keep buildings busy across multiple sports and age groups rather than those with the fanciest amenities. That reads correctly to me. The pattern matches what happens in adjacent real-asset businesses: capital-intensive, fixed-cost, local, and winner-take-most within a radius. Once a well-utilized complex opens within a 30-minute drive, a second one struggles to reach viable utilization, because the customer base (families willing to drive) is finite. This is a market where overbuilding punishes everyone, including the operator who built first.
The Pay-to-Play Substrate
Zoom out and the facility boom sits on a larger shift. Youth sports has moved decisively toward pay-to-play: private clubs have displaced school and municipal leagues as the primary development path in soccer, volleyball, baseball, and increasingly basketball. Families with disposable income buy better coaching, better facilities, and better exposure to college recruiters. The Aspen Institute's Project Play surveys have documented for years that household income is among the strongest predictors of youth sports participation, and that gap widened as club sports grew.
The facility investors are, in effect, monetizing that stratification. They are not creating it; parents' aspirations and the college-scholarship lottery created it decades ago. But every new $30 million complex raises the ceiling on what access costs, because competing for a roster spot increasingly means training in buildings that charge accordingly.
The odds deserve stating plainly. According to NCAA data, roughly 2% of high school athletes in most sports receive any Division I scholarship, and the fraction who go professional rounds to zero for practical purposes. Families are mostly not buying a career; they are buying participation, community, and structure, which are legitimate goods. The scholarship framing functions as marketing, and it is most aggressively marketed to the families least able to absorb the spend.
The Contradiction at the Center
Here is the tension the "recession-proof" framing skips. The sector's resilience claim depends on aspiration being durable, but the sector's growth depends on aspiration becoming more expensive. Those two forces pull against each other. A downturn that squeezes the middle-income family (the marginal customer who funds most of the volume) hits utilization, which hits the fixed-cost-heavy facility first, regardless of how emotionally essential sports felt in the good years.
The other open question is supply. Private equity discovered this sector the same way it discovered dental practices and HVAC: fragmented, cash-flowing, defensible locally. Consolidation tends to raise prices for the end customer, which narrows the base of families who can participate, which eventually undermines the aspiration narrative that justified the multiples in the first place. But nobody building these complexes seems to be stress-testing what happens when the marginal family says no.
What would actually test the recession-proof claim is a recession. Until one arrives, the label is a sales pitch dressed as a forecast, and the families writing the checks should read it as exactly that.
More Like This
K, C, or E? The Economy's Shape Debate, Explained
Economists are retiring the K-shaped recovery consensus. The C and E models now compete to explain who's gaining and who's still losing ground post-pandemic.
Supreme Court Blocks Trump's Bid to Fire Fed's Lisa Cook
The Supreme Court's 5-4 ruling blocking Trump's firing of Fed Governor Lisa Cook is a win for central bank independence—but a narrow, provisional one.
MIT's Blockchain Course Asks the Questions VCs Won't
MIT economist Robert Townsend's new blockchain course asks what distributed ledgers actually solve—a question the startup world has largely avoided answering.
How to Hire for Roles You've Never Done
Ryan Deiss paid a $200K CFO who was really a bookkeeper. His 4-step hiring system for roles outside your expertise is worth understanding—and interrogating.
Neros Plans to Build One Million Drones a Year
Neros CTO Olaf Hichwa on scaling drone production to 1M units annually, building for operators not bureaucrats, and why the US is losing the manufacturing race.
Enhanced Games Posts $62M Loss After Rocky Debut Event
Enhanced Group (NYSE: ENHA) lost $62M in Q2 2026 after a troubled debut event. Here's what the numbers reveal about the pro-PED sports league's shaky future.
Verda Raises €124M to Build European AI Cloud
Helsinki's Verda has stacked €124M in funding across two raises to build AI cloud infrastructure on clean Nordic power. Here's what the capital structure signals.
Quaise Energy Is Vaporizing Rock to Reach Geothermal Heat
Quaise Energy has raised $234M to drill geothermal wells using fusion-derived energy beams. Here's what's real, what's unproven, and what's at stake.