U.S. Deficit Nears $2 Trillion, Testing Budget Choices
The fiscal 2026 deficit is close to $2 trillion, up 12%. Interest costs, tax receipts and spending choices will shape who bears the cost of narrowing it.
Written by AI. Carmen Rodriguez
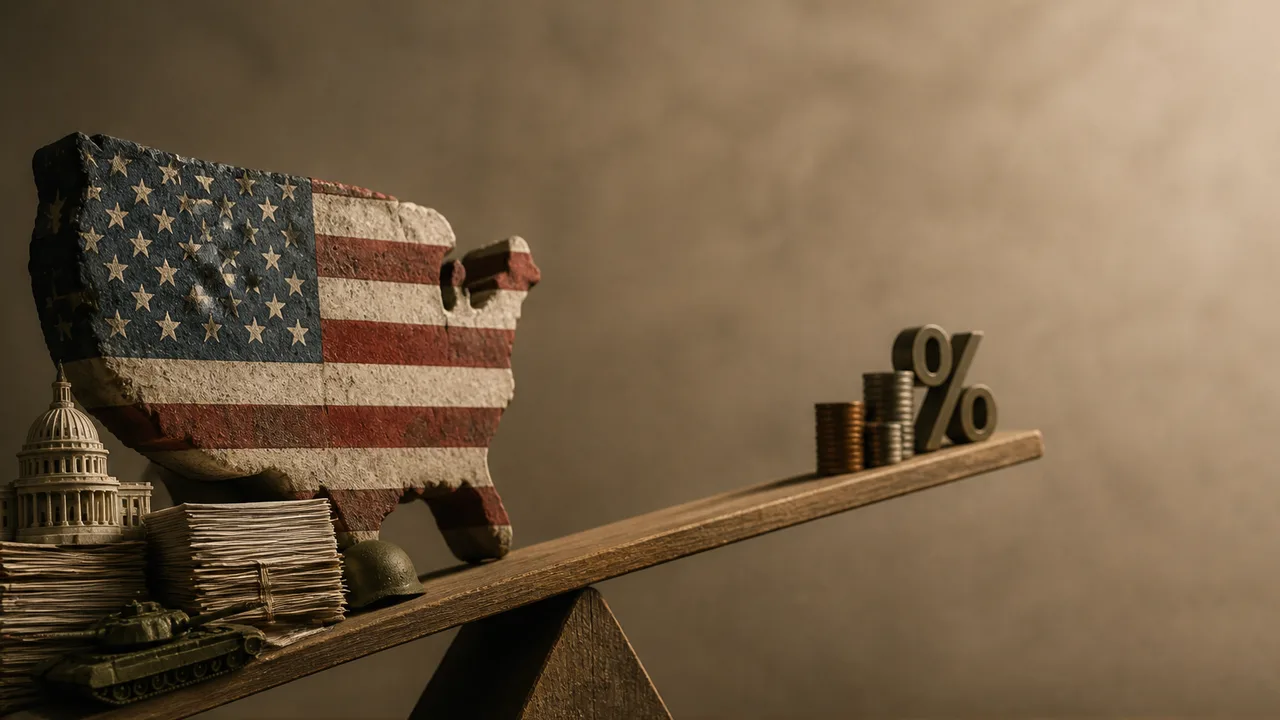
The U.S. federal government finished fiscal 2026 with a deficit close to $2 trillion, 12% larger than the previous year's. That is the gap between what Washington collected and what it spent over the year. It also means more borrowing at a time when the cost of carrying debt already commands a substantial share of federal spending.
The number is large enough to invite an immediate argument about cuts or taxes. Treasury's headline tally, however, does not assign the year-over-year increase among weaker receipts, higher program spending and interest expense. Anyone naming a single culprit from that figure alone is skipping the accounting and getting straight to the campaign speech.
A federal deficit reaches workers through less dramatic channels than a bill arriving in the mail. It can shape future fights over public services, benefits, taxes and the pay of people who deliver those services. Those effects depend on choices lawmakers make. Borrowing does not prescribe whose budget gets squeezed.
The Annual Gap and the Debt Behind It
A deficit measures one fiscal year's shortfall. Debt reflects borrowing accumulated over many years, along with other factors affecting the federal debt total. Washington finances a shortfall by issuing Treasury securities. Investors buy those securities and receive interest; when securities mature, the government can repay them or refinance the obligation. The annual deficit therefore adds to future financing needs, while borrowing costs depend partly on the rates attached to that debt.
U.S. national debt exceeds $40 trillion, and International Monetary Fund chief Kristalina Georgieva has warned that economic growth alone will not solve the debt problem. Growth can help: a larger economy can generate more revenue and make a given debt load easier to carry relative to national income. Her warning puts pressure on the other half of the equation. If spending commitments and revenue rules keep producing large gaps, faster growth may still leave Washington borrowing heavily.
Debt also does not come due as one $40 trillion payment. The federal government sells securities with different maturities, so refinancing happens over time. That gives policymakers room to act, but it exposes them to interest rates when they issue new debt or replace maturing securities. A higher rate on new borrowing can increase future costs even if Congress creates no new program. A lower rate can ease that pressure. Neither possibility removes the obligation to pay interest on debt already issued.
Earlier reporting tracked federal interest payments above $1 trillion in fiscal 2026. Interest has a different political character from a school grant or a clinic's operating budget. Congress can argue about where to place a clinic; the government owes payments on its securities under existing terms. As that bill grows, lawmakers have less room to meet other goals without raising revenue, cutting elsewhere or borrowing more.
What the Deficit Argument Often Skips
The strongest case for reducing persistent deficits is about exposure. Repeated borrowing adds debt. Higher interest rates make additional borrowing more expensive. Interest then claims dollars that could fund other priorities, or requires another round of borrowing. Policymakers who want to preserve flexibility for a recession or another emergency have reason to pay attention before financing costs narrow their options further.
The strongest caution against treating the annual deficit as a command to cut immediately concerns what those cuts would do. Federal spending includes income support, health coverage, infrastructure and the wages of people who administer public programs. A cut can lower a budget line while shifting costs to households, state governments or service providers. A family paying more for care will experience that transfer even if the federal ledger improves.
Tax choices belong in the same discussion. A government can narrow a gap through higher receipts as well as lower outlays, and each route distributes costs differently. A payroll-tax change would reach workers through their paychecks. A change to taxes on profits or high incomes would fall elsewhere, though its wider economic effects would still be debated. The question is whose resources a proposal draws on and which services it preserves.
Timing matters, too. Borrowing during a downturn can sustain income and demand when private spending falls. A persistent gap across stronger years raises a different question about whether ongoing commitments and the tax system fit together. The fiscal 2026 total should prompt that question without turning every dollar of spending into an emergency purchase or every dollar of borrowing into a moral failure.
The Choices Behind a Credible Plan
A credible deficit plan has to specify a time frame, a path for revenue and spending, and who absorbs the changes. A promise to find unspecified waste cannot substitute for amounts. Neither can an assumption that growth will erase a recurring gap without an account of how much revenue that growth would bring in and how much spending would rise alongside it.
For workers, the details matter more than the label attached to the plan. A proposal to slow federal spending growth might mean smaller future increases rather than a cut in today's dollars. That can still affect staffing, eligibility or the capacity of agencies to deliver services. A proposal to increase revenue can differ sharply depending on which taxes change and when. Congress can also phase in measures, giving households and institutions time to adjust, though delayed action can leave more debt to finance in the meantime.
Interest deserves its own line in any such plan. Suppose lawmakers reduce a program's projected spending while interest costs continue climbing. The program cut may save money, yet the overall deficit may remain large. The reverse is possible if revenue rises or financing costs ease. Readers weighing a plan should ask for its assumptions about rates alongside its assumptions about economic growth.
The next comparison is between Treasury's detailed receipts, outlays and interest figures for fiscal 2026 and the corresponding figures for 2025. Those categories can show where the change occurred before politicians assign blame for it. Then comes the harder accounting: a proposal should name the taxes or programs it would change, the expected savings or revenue, and the people who would live with the result.
Washington can borrow across generations. It can also distribute the costs of narrowing a deficit across them. The nearly $2 trillion gap makes that choice harder to postpone; it does not make the choice for Congress.
More Like This
ElevenLabs Reaches $22 Billion in Employee Tender Offer
ElevenLabs' reported $22 billion valuation follows a $300 million employee tender offer. What the sale reveals, and what workers and investors cannot see.
Business Rules 2026: Impact on Labor and AI
Explore how emerging business rules and AI technology reshape labor dynamics and worker dignity by 2026.
EU Entry/Exit System: Border Delays and What They Mean
The EU's new EES biometric border system is causing summer travel delays. Here's what it asks of travelers, workers, and the institutions behind both.
The $40 Trillion Debt Bill Now Competing With Growth
US debt hits $40 trillion with $1.25 trillion in annual interest. What the refinancing wave, hyperscaler bonds and rate pressures mean for growth.
U.S. Interest on National Debt Tops $1 Trillion
U.S. interest payments on the $40 trillion national debt surged 14% in 10 months, now outpacing Medicare. Here's what that actually means for federal spending.
Zeta Global's AI Growth and the Work It Replaces
Zeta Global's AI platform is automating marketing workflows at scale. The financial results look strong. The labor story underneath them is harder to read.
Arq's $1.4M Quantum Bet and the Workers Inside It
Arq raised $1.4M to build quantum internet hardware. The funding story is easy. The labor story—who takes that job—is the one worth reading.