Kalshi's Margin Trading Bid Draws a Line Around Sports
Kalshi wants CFTC approval for leveraged event contracts. Its sports carveout, collateral plan and institutional focus show who gains first and who bears risk.
Written by AI. Jin Seo
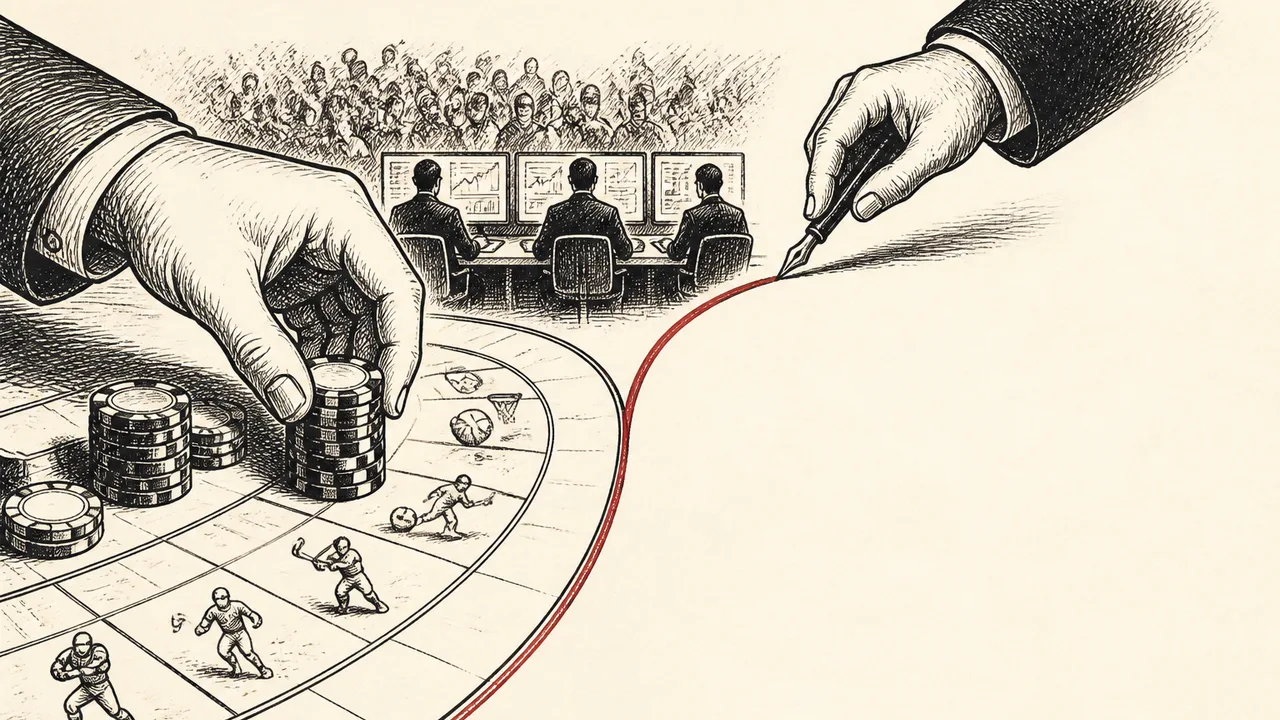
Kalshi asked the Commodity Futures Trading Commission on September 22 to let some traders use leverage on its event contracts, opening a regulatory path toward prediction markets funded partly with borrowed money.
The request came through Kalshi Klear, the platform's internal clearinghouse. Under the plan described by Kalshi to CNBC, access would be restricted to self-clearing members with direct relationships to Kalshi Klear and enough capital to meet thresholds that have yet to be disclosed.
The initial audience would therefore be narrow. Ordinary customers wagering on a match or an awards show would not receive a new credit line. Kalshi says sports, culture and “mention” contracts would remain outside the margin program.
Those exclusions sketch the business strategy more clearly than the word “leverage” does. Kalshi is protecting the retail-heavy sports operation that helped build its volume while creating a separate lane for institutions interested in longer-dated questions. The filing asks regulators to let prediction markets borrow one of Wall Street's favorite tools without immediately extending it to the platform's most gambling-adjacent products.
What Would Change
Regulated U.S. event contracts are currently fully collateralized. A trader must provide cash covering the position rather than gaining larger exposure with borrowed funds. That arrangement puts a hard ceiling on how much exposure a given amount of cash can purchase.
Margin removes that ceiling. If a trader can control a larger position than its posted collateral would otherwise support, the same pool of capital can back more trading. It also creates a gap between the exposure and the cash standing behind it. Managing that gap becomes the clearinghouse's problem when a position moves sharply against a member.
Kalshi proposes increasing collateral requirements as a contract approaches settlement. The logic is understandable: an event contract can reprice rapidly when the answer becomes known, leaving less time to demand more collateral or close a losing position. Higher requirements near expiry would reduce that exposure.
The available descriptions leave several consequential questions unanswered. Kalshi has not disclosed the capital thresholds, the maximum leverage, the schedule for raising collateral or the procedures for handling a member default. Without those terms, the tiered system is a design outline rather than a measurable risk-control regime. CFTC approval is also pending.
The restrictions serve two purposes at once. They limit direct access by ordinary users, reducing the immediate consumer-borrowing concern. They also make the proposal more attractive to regulators by placing the first layer of loss absorption with capitalized firms that have direct clearing relationships.
That does not remove risk. It changes who is permitted to take it and gives Kalshi Klear responsibility for policing the boundary.
A Large Market Goes Looking for Larger Traders
Kalshi's timing follows a steep expansion in reported activity. A Quartz report carried by Yahoo Finance said the company accounts for more than 90% of U.S. prediction-market activity and that its annualized trading volume rose from $52 billion to $178 billion in six months.
That is roughly 3.4 times the earlier annualized rate. The figure describes a run-rate estimate, not $178 billion of completed trades during those six months, and the available reporting does not provide the underlying monthly series. It still shows why institutions have appeared on the guest list. Large traders generally need enough activity on the other side of a market to enter and exit without moving prices too far.
Sports trading supplied much of the industry's recent growth. Another account said activity on Kalshi and rival Polymarket surged during 2026 with help from the World Cup and other sports wagering. Kalshi's decision to exclude sports from margin therefore separates the volume engine it already has from the institutional business it wants to build.
The resulting structure would resemble two markets sharing an exchange. Retail customers could continue funding sports contracts in full. Approved self-clearing members could use leverage on eligible contracts, including the longer-dated markets Kalshi says institutions find more appealing.
That reading remains an inference from the proposed exclusions and the company's stated institutional goal. Kalshi has not published a forecast showing how much leveraged volume it expects or which contracts would qualify.
The competitive pressure extends beyond Kalshi. Polymarket moved in July to obtain licenses that could eventually support margin on U.S. event contracts, according to the CNBC and Quartz accounts. Kalshi already offers leverage on perpetual futures and has introduced professional trading tools with deeper order-book information and risk controls. Margin on event contracts continues that progression from a cash-backed prediction venue toward the infrastructure familiar to derivatives desks.
The Wall Street Comparison, with Limits
Stocks and derivatives provide the obvious comparison because margin is standard practice in those markets. Institutions use it to avoid tying up the full value of every position. Kalshi's proposal borrows that capital-efficiency argument and the language of clearing members, collateral requirements and default management.
Event contracts introduce a different settlement pattern. A stock can trade indefinitely, while an event contract approaches an answer and then settles. Kalshi's plan to demand more collateral near expiry reflects that compressed timeline. The closer the contract comes to resolution, the less room the clearinghouse has to correct a collateral shortfall after a sudden price move.
The comparison also has a retail limit. Margin accounts are available to individual stock traders through brokerages, while Kalshi's described program would begin with qualifying self-clearing members and exclude sports, culture and mention markets. Approval under those terms would establish institutional leverage before broad consumer access.
That narrower design answers part of the criticism aimed at borrowed betting. A Cryptoprowl article carried by Yahoo Finance cited warnings from unidentified analysts and politicians that leverage could worsen gambling addiction and lead people to borrow at high interest rates. The article did not name those critics or provide evidence about likely harm under Kalshi's proposed restrictions, so the warning should be read as a policy concern rather than a demonstrated outcome of this filing.
Kalshi's sports exclusion and membership requirements reduce the direct fit between that critique and the first version of the plan. They do not answer whether access could expand later, whether leveraged firms might transmit losses elsewhere or whether more institutional trading would change prices faced by fully collateralized customers.
The source of the proposal's public framing also deserves disclosure. CNBC received Kalshi's memo and spokesperson confirmation, and CNBC says it has a customer-acquisition relationship with Kalshi and holds a minority investment. That commercial connection does not negate the reported filing details, but it gives readers reason to separate confirmed terms from Kalshi's argument that leverage is necessary to attract institutions.
For the CFTC, the central question is narrower than whether prediction markets look like betting or finance. The agency must decide whether Kalshi Klear can monitor leveraged event positions, collect enough collateral as settlement approaches and contain losses when a member's cash falls short.
For everyone else, the filing shows where the sector wants to go. Retail sports trading supplied the crowd. Kalshi now wants institutions to arrive with borrowed capital, subject to a velvet rope whose height the company has not yet disclosed.
More Like This
US Open Partners With Kalshi in Prediction Market Deal
The USTA signed Kalshi as the US Open's exclusive prediction market partner days before the 2026 main draw. Here's what it signals for tennis and sports media.
L Catterton's HYROX Bet: When Fitness Racing Grows Up
A consortium led by L Catterton has bought Infront's majority stake in HYROX. What the deal says about scaling mass-participation fitness racing.
States Can Now Regulate Prediction Markets as Gambling
A federal appeals court ruled states can regulate prediction markets as gambling. Here's what Kalshi users need to know right now, and what to watch next.
Inside the Kalshi NFL Prediction Market Bot Challenge
Exploring the real-time data challenges of building a Kalshi NFL prediction market bot.
The CLARITY Act Failed. Regulators Now Set the Rules
The Senate stalled the CLARITY Act over ethics and banking fights, leaving crypto rules to agencies while key investor protections remain unresolved for now.
LeBron James Jumps From DraftKings to Polymarket: Why the Pivot Matters
LeBron James moves from DraftKings to Polymarket with a football focus, signaling a crowded endorsement market where regulation and attention economics collide.
Vetting Expired Domains in iGaming SEO
Craig Campbell explains why domain rating misleads iGaming SEO buyers, what the Wayback Machine reveals, and how to vet expired domains before spending.
Auditing Vibe-Coded Apps Without Reading Them
A Brainqub3 video argues you can safely ship 100k-line AI-generated codebases without reading them. The framework is sound. The business model behind it is worth examining.