Why BRICS De-Dollarization Still Runs Through the Dollar
BRICS wants more trade in local currencies, but liquidity, hedging and settlement barriers keep the dollar central, with consequences for workers and firms.
Written by AI. Carmen Rodriguez
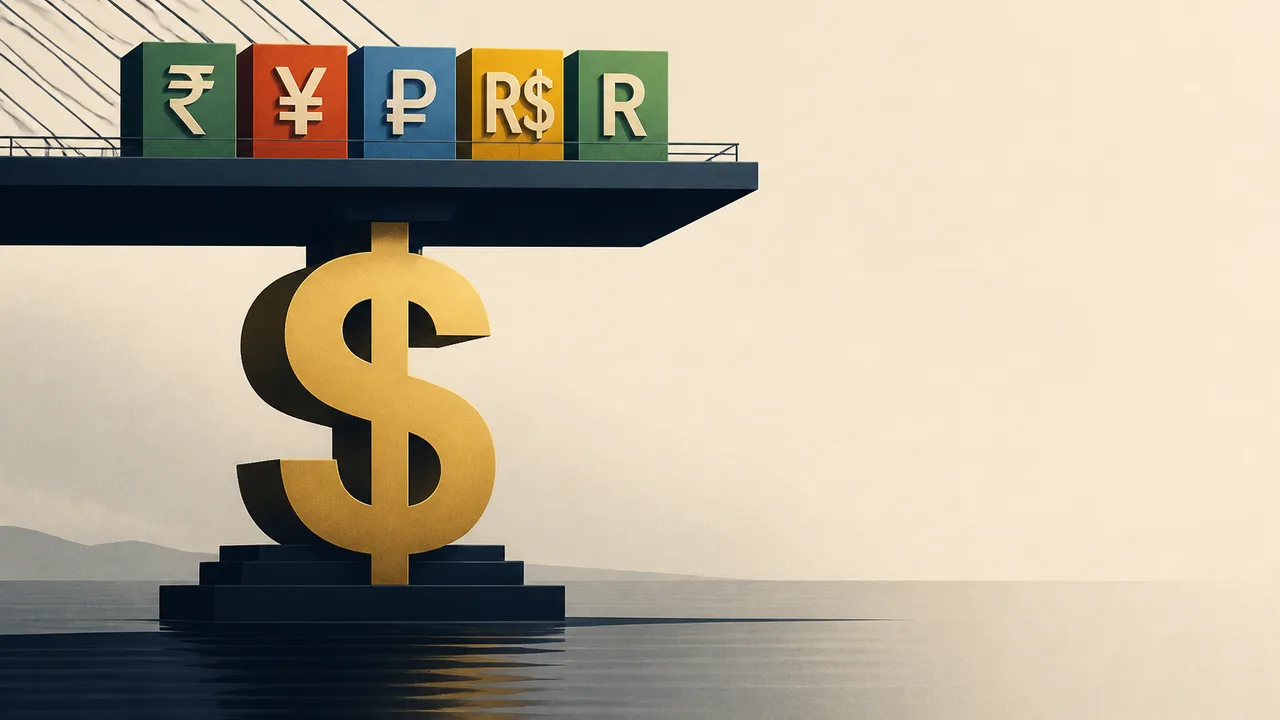
BRICS leaders are again pressing for greater use of local currencies in cross-border trade. For workers at an import-dependent factory, that summit language can eventually arrive as a delayed input order, fewer production shifts or pressure on payroll.
Currency plumbing sounds remote until a company cannot obtain the foreign exchange needed to buy fuel, fabric, chemicals or machine parts. The invoice currency determines what the buyer must acquire, the exchange rate determines the bill, and access to settlement channels determines whether the supplier gets paid. Employers decide how to distribute those costs, but workers often meet them first through reduced hours, slower hiring or demands for concessions.
The political case for reducing reliance on the dollar is straightforward. Governments want more control over cross-border commerce, particularly when dollar-based financial channels leave them exposed to decisions made in Washington or to institutions outside their jurisdiction. According to CNBC, BRICS leaders have continued to promote local-currency trade as part of that effort.
Yet an exporter does not accept a currency because a communiqué gave it a stirring paragraph. The exporter wants to know whether the currency can be converted, invested, hedged and moved through a reliable payment system. Until those questions have satisfactory answers, the dollar keeps getting the purchase order.
What Makes a Currency Useful Abroad
International currency use rests on an ecosystem rather than a proclamation. Banks need access to the currency. Traders need liquid foreign-exchange markets. Companies need contracts they can enforce and instruments that protect them against exchange-rate swings. Investors need assets in which they can hold the proceeds.
The dollar benefits from the scale of dollar-denominated markets and from habits built across decades of trade and finance. A company quoting a shipment in dollars can usually find banks, payment infrastructure and hedging products designed around that choice. Buyers and sellers may have complaints about the system while continuing to use it because switching carries costs of its own.
This helps explain the contrast identified by Firstpost: discussion of moving away from the dollar has grown louder, while the currency remains deeply embedded in global commerce.
Reserve currency, invoicing currency and settlement currency also describe different jobs. A central bank can diversify its reserves while domestic importers keep receiving dollar invoices. Two governments can arrange settlement in local currencies while companies price the underlying goods in dollars. A payment may travel through several conversions before reaching the seller.
A headline announcing local-currency trade therefore leaves several practical questions unanswered. Who holds the currency at the end? Can that holder spend it on imports, invest it in a liquid asset or convert it without taking a large loss? Who supplies emergency liquidity when markets seize up? Who bears the exchange-rate risk between order and delivery?
Bilateral Trade Meets an Accounting Problem
Local-currency settlement works most smoothly when trade flows offer each participant a use for the other's money. Persistent imbalances make the arrangement harder.
Suppose Country A imports far more from Country B than it exports there. Companies in A can pay in A's currency, but exporters in B will accumulate balances they may struggle to spend. They can seek conversion into another currency, demand a higher price to cover the risk or decline the arrangement. A third currency can reappear at the back of the transaction after disappearing from the front.
Currency-swap agreements can help central banks and commercial banks bridge those mismatches. They still require negotiated limits, credible counterparties and decisions about exchange rates, maturity and repayment. A swap line provides machinery for a relationship; it does not create balanced trade or automatic confidence in the currencies involved.
Businesses add another constraint. A finance ministry may prefer local-currency settlement for strategic reasons, while a manufacturer prefers dollars because its raw materials, loans and hedges already use dollars. Changing the invoice currency can create a new mismatch on the company's books.
That commercial resistance does not prove that diversification will fail. It establishes the price of success: alternative currencies need liquidity, financial instruments, predictable access and institutions that businesses will trust after the summit delegation has gone home.
BRICS is Proceeding More Carefully than the Rhetoric Suggests
BRICS contains economies with different trade profiles, financial systems and political priorities. The group has no shared central bank, common treasury or unified legal regime. Those absences matter because a common or widely used currency requires decisions about issuance, liquidity, governance and losses. Those are power questions wearing accounting glasses.
The bloc's formal language reflects some of that caution. Deccan Chronicle reported that the joint position from BRICS finance ministers and central bank governors was more restrained than years of speculation about a direct challenge to dollar dominance.
Greater local-currency use remains a narrower and more achievable objective than creating a shared BRICS currency. Governments can expand bilateral settlement, connect payment systems or encourage banks to offer more products in participating currencies. Each step can reduce dollar use in selected transactions without supplying a universal replacement.
That distinction also clarifies what gradual erosion would look like. The dollar could lose share transaction by transaction as firms gain workable alternatives. No dramatic handover is required. But a collection of bilateral arrangements can remain fragmented, expensive and dependent on eventual conversion into dollars. Counting agreements alone would overstate the change.
Publicly available payment data can show currency shares across some networks and transaction categories. It does not provide a complete, comparable ledger covering every BRICS trade invoice, currency swap, conversion and final settlement. The public record described by the three reports establishes continued political interest and institutional caution. It does not establish a rapid, system-wide migration away from the dollar.
The Exchange Rate Eventually Reaches the Time Clock
Consider an illustrative garment factory in a BRICS country. The factory pays workers in local currency but imports dye and replacement parts from a supplier that invoices in dollars. Its bank has limited dollar availability, so the input order waits or costs more to finance. Management can absorb the expense, raise prices, seek a different supplier, reduce production hours or delay investment. The currency problem becomes a workplace problem through that chain of choices.
Now suppose the two countries establish local-currency settlement. The factory can pay without first buying dollars, and the order may move faster. The improvement lasts if the overseas supplier can use, invest or readily convert the currency it receives. If the supplier immediately trades that payment for dollars, the dollar demand has shifted to another institution and another point in the chain.
Workers have little control over the invoice currency, the bank's foreign-exchange allocation or the hedge purchased by the finance department. Their bargaining power influences whether an exchange-rate shock comes out of profits, prices, staffing or wages. A collective agreement with guaranteed hours or consultation rights can change that allocation; an unorganized workforce may receive the decision as a posted schedule.
This is why the durability of any de-dollarization project will show up beyond central-bank statements. It will appear in routine commercial behavior: the currency on supplier contracts, the cost of hedging, the speed of settlement and the willingness of firms to retain what they receive.
For the worker waiting to learn whether next week's production line will run, the test is brutally practical. Can the employer buy the inputs, clear the payment and fund payroll without turning a currency-policy experiment into somebody else's lost shift?
By Carmen Rodriguez
More Like This
Business Rules 2026: Impact on Labor and AI
Explore how emerging business rules and AI technology reshape labor dynamics and worker dignity by 2026.
Dubai's Crisis Has a Worker Problem No One's Covering
Dubai's economic model was built on migrant labor with almost no rights. Now, with airstrikes and a blockaded strait, those workers face the worst of the fallout.
Financial Crises Follow Patterns — But Not for Everyone
Kuran Francis maps four recurring patterns behind every major financial crisis. The framework is solid. What it leaves out is the story of who pays when the system breaks.
Wall Street Knew the Crash Was Coming. Saying So Got You Fired.
Jeremy Grantham's famous poll revealed 398 analysts knew the dot-com crash was guaranteed. A 2003 study shows why none of them said so publicly: accuracy cost careers.
Gen Z's Dating Retreat Is Also an Economy Story
Gen Z isn't just retreating from dating—they're optimizing themselves for a labor market logic that's colonized their bodies. Christine Emba unpacks what's actually happening.
AI and Gaming: A New Frontier for Work and Play
AI in gaming reshapes job roles, user engagement, and societal impacts. Explore the nuances.